
What Farmers Should Check Before Signing a Crop Insurance Claim
Introduction
A crop insurance settlement can feel like the end of a difficult season: the adjuster has inspected the fields, the amount is on paper and payment may be close. But a signature can have consequences that aren’t obvious from the headline figure. Before signing, make sure you understand what loss the insurer has accepted, what it has excluded and whether the documents match the policy and the evidence from your farm.
Crop insurance claims depend on details such as acreage, production records, planting dates, damaged samples and policy provisions. A missed field, incorrect unit or unexplained deduction can affect the result. The goal isn’t to obstruct a fair settlement, but to make sure the record reflects what happened and that you understand what your signature means. Reviewing crop insurance claims carefully can help you spot errors before they affect a settlement.
The farmer’s and adjuster’s perspectives
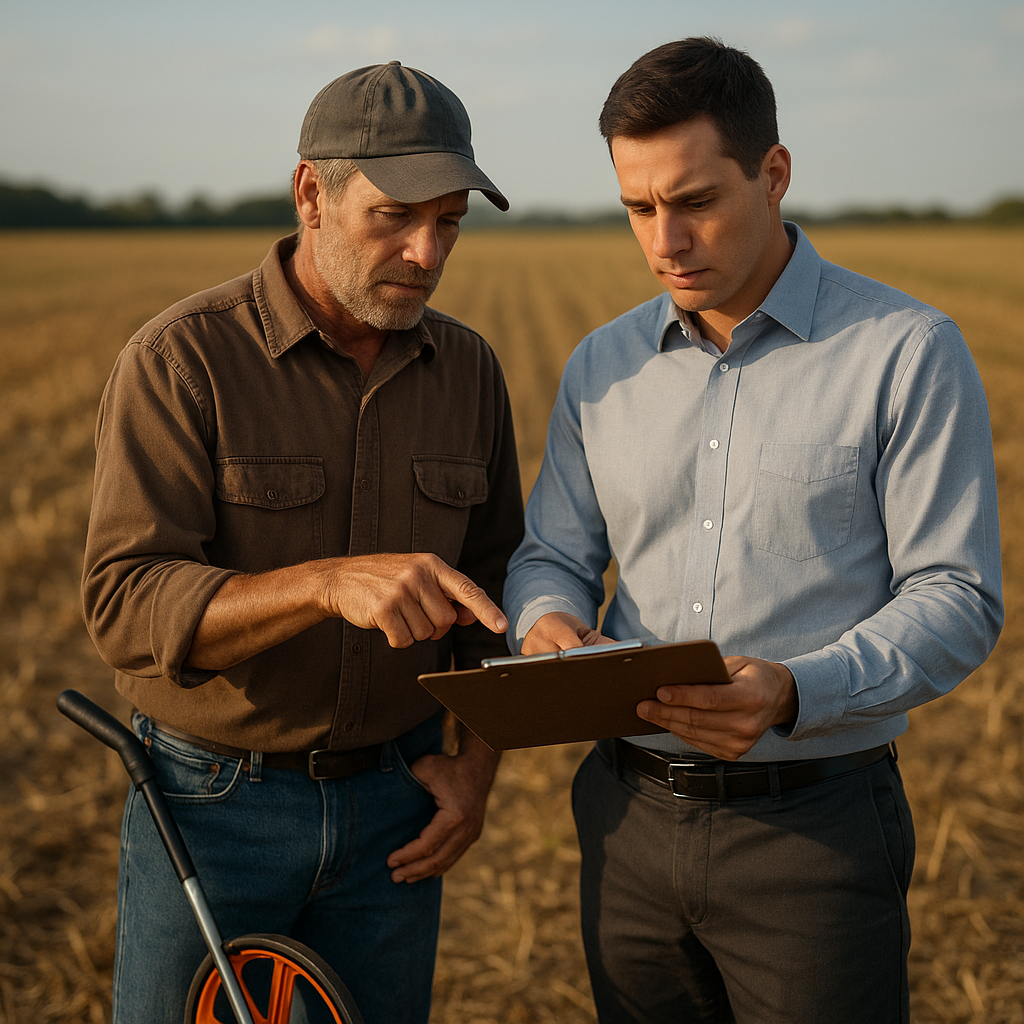
The farmer and the adjuster bring different responsibilities to a claim. The farmer knows the planting history, field conditions and decisions made during the season. The adjuster must apply the policy, document the loss and support the insurer’s calculation. Both perspectives matter when reviewing crop insurance claims, so check the claim against the field evidence and the policy language.
A general description of the farmer’s role in agricultural production helps explain why records may cover multiple fields or stages of work. For insurance purposes, though, the policy definitions and your farm’s records are what count. Check that the claim identifies the correct insured person or entity, crop, acreage and coverage unit. Accurate identification is a basic step in documenting crop insurance claims.
Read the entire form rather than relying on a verbal summary. Check whether it is a loss statement, an authorization, a release or an acknowledgement of payment. If a clause is unclear, ask the insurer or agent to explain it in writing. Don’t assume your signature only confirms receipt of funds; the effect may depend on the wording used for crop insurance claims.
Key factors
1. Damage assessment. Compare the adjuster’s notes and measurements with your records. Check which fields were inspected, the acreage assigned to each, the inspection date and the method used to estimate damaged or remaining production. If part of a field was inaccessible or conditions changed after the inspection, make sure that’s noted. A careful damage assessment gives both parties a clearer basis for evaluating crop insurance claims.
Photographs, dated field notes, harvest records and relevant weather information can support your account of the loss. Preserve original files where possible, including timestamps and location details. Don’t alter records to fit a calculation. Instead, identify discrepancies and explain them with supporting evidence that can be added to your crop insurance claims file.
2. Claim documentation. Check that the paperwork includes the production figures and other inputs used to calculate the indemnity. Compare them with scale tickets, delivery statements, farm logs and any records required by the policy. Look for missing loads, duplicate entries, incorrect units or production assigned to the wrong field or unit. Complete claim documentation makes it easier to review crop insurance claims and verify the calculation.
Ask for a written breakdown of the calculation, including the applicable guarantee, recognized production, price or valuation method, and each deduction. The formula depends on the policy and coverage selected, so a figure that looks familiar from another season may not apply. Keep copies of everything you submit and every version of the insurer’s calculation for your crop insurance claims records.
3. Policy terms and exclusions. Read the settlement alongside the policy, endorsements and applicable notices. Confirm the insured cause of loss, coverage dates, reporting requirements and, where relevant, how prevented planting, replanting or quality adjustments are treated. An adjuster’s summary may not include every provision that affects crop insurance claims or the final amount.
4. Deadlines. Note the dates for reporting damage, submitting records, responding to a determination and requesting a review or appeal. Insurance deadlines vary by policy, insurer and jurisdiction, so don’t rely on a general rule or informal assurance. If a deadline is near, ask promptly how to preserve your right to challenge or supplement the file. Keep proof of when communications were sent and received, especially for time-sensitive crop insurance claims.
5. Your rights and disputed amounts. Ask what your signature confirms and whether accepting payment affects your ability to dispute part of the claim. Farmer rights depend on the document and applicable rules: a check, receipt and release aren’t interchangeable. If the form appears to waive rights or close the claim, seek clarification before signing and consider consulting a qualified legal or agricultural insurance adviser.
Describe any payout dispute specifically: identify the line item, the evidence that conflicts with it and the correction you’re requesting. Payout disputes involving crop insurance claims are easier to assess when you identify a specific issue, such as acreage, production, cause of loss or policy interpretation, rather than simply saying the payment is too low. Keep your comments factual and retain a dated copy.
How the claim can unfold
Compare the written calculation with your farm’s evidence, rather than making the review about personalities. In a straightforward case, field measurements, production records and policy terms align. You verify the figures, sign an accurate acknowledgement and keep a complete copy. The paperwork for crop insurance claims should explain the result, not just accompany an offer of payment.
In a more difficult case, the adjuster’s estimate may omit a damaged section, use the wrong acreage or rely on production records you believe are incomplete. Pause, identify the discrepancy, gather supporting records and ask for a written explanation or revised assessment. If the disagreement remains, follow the policy’s review process for crop insurance claims and meet every deadline.
This approach supports both accuracy and credibility. If you sign without understanding the document, it may be harder to show what you accepted. Preserving evidence and making specific objections gives the insurer a clearer basis to reassess crop insurance claims. If the stakes are significant or the wording is ambiguous, independent professional advice can help you understand the policy before a decision becomes difficult to reverse.
Conclusion
Before signing a crop insurance claim, verify the damage assessment, acreage, production figures, calculation, policy terms and deadlines. Make sure you understand what your signature acknowledges and whether any wording limits further review. Careful documentation can’t guarantee a particular outcome, but it can help uncover errors in crop insurance claims while there’s still time to address them.
Don’t judge the settlement by whether it seems fair at first glance. Check whether the amount and paperwork match the policy and the facts. Read every page, request explanations in writing and keep a complete record. Your signature should reflect an informed decision, not be the first time you discover what the claim says.